
Car Ownership Through Every Life Stage: How Your Needs Change Over Time
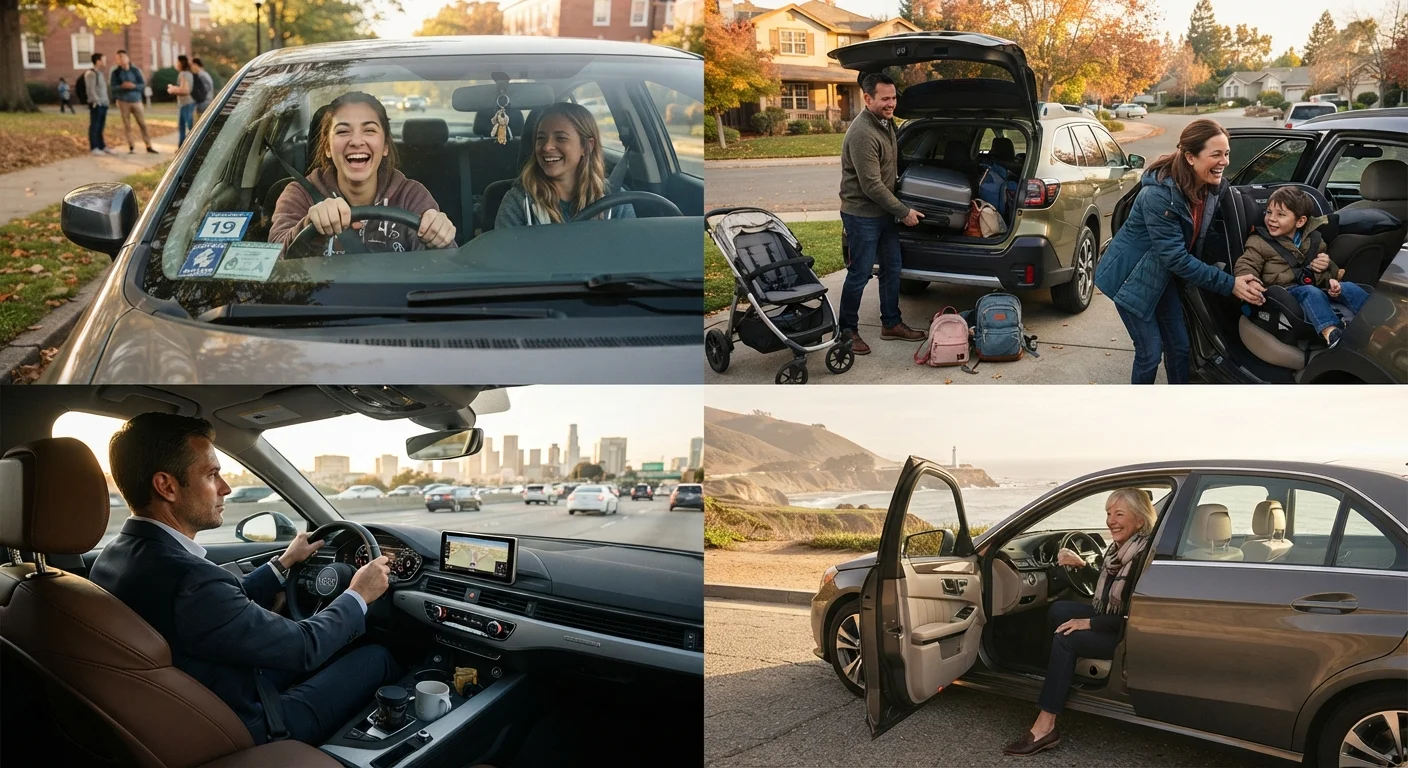
Photo credit: TrendingFaqs.com
In this article
From a first car at 16 to retirement driving, how the practical and financial side of car ownership shifts across life stages.
Key Takeaways
- Your financial capacity, driving patterns, and safety needs all shift across life stages.
- First-car buyers benefit most from reliability and low insurance costs, not features.
- Families often underestimate how much the right vehicle format affects daily life.
- Mid-life is often when total cost of ownership becomes the clearest decision factor.
- Older drivers may benefit from vehicles with stronger driver-assistance technology.
- Reviewing your car situation every few years can prevent costly mismatches.
Why life stage shapes car decisions
A car is one of the largest recurring expenses most Americans carry. What makes it unusual is that the right vehicle at one point in life can be genuinely wrong a decade later. A two-door coupe that worked perfectly at 22 may not fit a car seat. A pickup truck ideal for hauling in your forties can feel like too much to manage at 75.
The financial side shifts just as much as the practical side. Insurance rates change with age and driving record. Loan terms that made sense on a starter salary may look different once income stabilizes. Maintenance costs tend to grow as a vehicle ages, and older drivers may weigh those costs differently than younger ones. Thinking about car ownership as something that evolves, rather than a static decision you make once, helps you avoid paying for a vehicle that no longer fits your life. The hidden costs of car ownership compound over time, and they hit differently depending on where you are in life.
The first car: teens and early twenties
For most people, a first car means one thing above everything else: getting around independently. The emotional weight of that milestone often pulls people toward vehicles they cannot realistically afford or insure. The practical calculus at this stage is straightforward. Insurance is expensive for young drivers, typically significantly higher than for drivers in their thirties, so a vehicle that is cheap to insure matters more than most buyers realize. Cars with good safety ratings and modest engine sizes generally cost less to insure.
Reliability comes second. A first-car owner is still learning how to notice problems before they become expensive, so a vehicle with a proven track record reduces the risk of a breakdown that wrecks a tight budget. Our guide to first-time car owner maintenance basics covers the upkeep habits worth building from day one.
Budget discipline matters here more than at any other stage. Monthly payments, fuel, registration, insurance, and maintenance all compete with rent, student loans, and other early-adult costs. The first year of car ownership often brings surprise expenses that new owners underestimate.
When buying a first car, get an insurance quote before signing anything. The premium can be high enough to make an otherwise affordable car unworkable on a tight budget.
Insurance costs for young drivers can rival or exceed a monthly car payment, and many buyers do not find this out until after the purchase is complete.
Before trading in a paid-off vehicle, list every repair it has needed in the past two years and compare that total to what a new loan payment would cost annually.
A working paid-off car almost always costs less per year than a new loan, but the break-even point shifts once repair costs become frequent or unpredictable.
The young professional years
Once income stabilizes and a driving record builds some history, insurance costs start to fall. This stage often brings the first real choice between a new and a used vehicle. A used car purchased carefully can offer better value, but that comparison has real trade-offs that go beyond the sticker price. The new versus used car decision deserves more analysis than most buyers give it at this stage.
Commuting patterns tend to define what a vehicle actually needs to do during these years. A long daily highway commute favors fuel efficiency and comfort. A short urban commute may make parking footprint and maneuverability more important than anything else. People who work remotely may find they drive far less than expected, which changes the math on depreciation and cost-per-mile considerably.
This is also the stage where financial goals compete most directly with car spending. A vehicle that consumes too large a share of take-home pay can slow progress on other savings targets. The savings goals by life stage framework is a useful check: if car costs crowd out savings for an emergency fund or retirement contributions, the vehicle is probably too expensive for this moment.
Family life and the vehicle pivot
A growing family is one of the clearest prompts to reconsider a vehicle. Car seats require rear-door access and specific interior dimensions. Cargo space that seemed adequate before becomes a constant frustration. Road trips with children introduce new requirements around comfort and entertainment systems that feel trivial until you are on hour six of a twelve-hour drive.
Many families move toward minivans, crossovers, or three-row SUVs during this period, and each format involves real trade-offs in fuel costs, parking difficulty, and purchase price. The insurance picture also changes: adding a teenage driver to a family policy later in this stage can be one of the largest single insurance cost increases a family faces.
Safety ratings become more important when children are regular passengers. Federal agencies publish crash test results that are publicly available and worth reviewing before a purchase. The specific configuration of a vehicle, how many rows, what kind of doors, where the seatbelt anchors sit, often matters more than the brand name on the hood.
Mid-life ownership: costs, reliability, and decisions
By mid-life, most drivers have a clearer picture of their actual driving habits. Children may be older or gone from the household. Commutes may have changed. The vehicle that made sense five years ago may now be oversized, underused, or carrying maintenance costs that have started to climb.
This is often the stage where total cost of ownership becomes the sharpest lens for a car decision. A vehicle that is paid off but costs $3,000 a year in repairs may or may not beat a new loan payment, depending on the specific numbers. That comparison requires honest accounting of all ownership costs, not just the obvious ones.
For drivers who keep vehicles for a long time, mid-life is also when timing belts, transmission services, and other major interval maintenance items tend to come due. Staying current on those services extends vehicle life considerably. The car maintenance hub covers the service intervals worth tracking.
Driving in retirement
Driving patterns often change substantially in retirement. Without a daily commute, annual mileage can drop sharply, which affects both fuel costs and how quickly a vehicle depreciates. Some retired drivers find they need only one vehicle where two once made sense, which changes the household transportation budget considerably.
Physical considerations also enter the picture. Entry and exit height matters more for people with joint pain. Visibility, parking assist systems, and automatic emergency braking have practical value for drivers who want to extend their safe driving years. These are not features to dismiss as luxury items; they are tools that address real changes in reaction time and physical flexibility that come with age.
Some older drivers also face the question of when to stop driving altogether, or when to limit driving to familiar routes and daylight hours. That decision is personal and medical, best made with input from a physician and family rather than from outside pressure. From a financial standpoint, giving up a vehicle entirely can free up meaningful income, though it requires a realistic plan for transportation alternatives in the area where a person lives.
Author
Cars Editorial Team
Cars Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →