
First-Time Car Owner? Here Is What to Expect in Year One
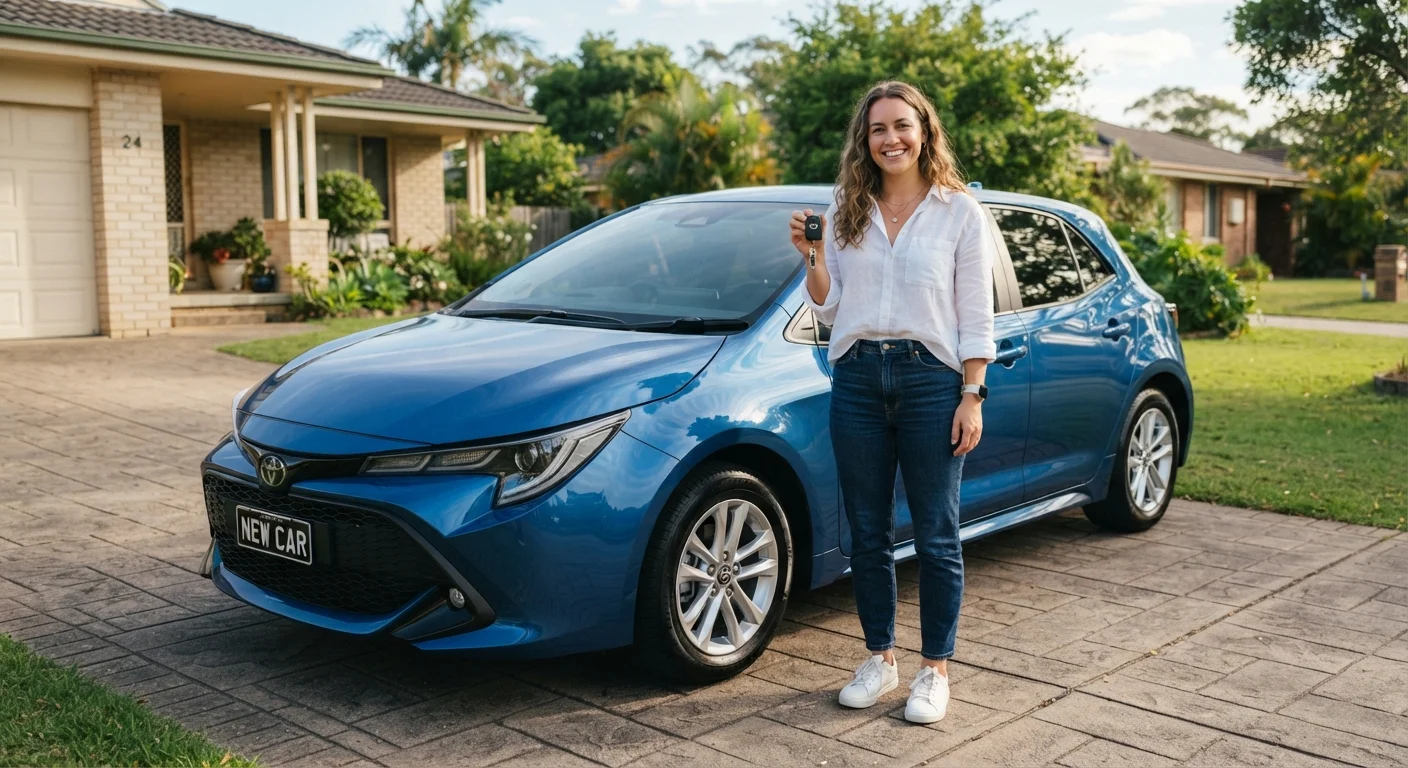
Photo credit: TrendingFaqs.com
In this article
From registration deadlines to routine maintenance, a practical introduction to the real costs and responsibilities of owning a car.
Key Takeaways
- Registration and title deadlines vary by state and missing them usually means late fees.
- Auto insurance is required in nearly every state, and minimum coverage may not be enough protection.
- Most new cars need an oil change, tire rotation, and cabin filter replacement within the first year.
- Beyond the car payment, new owners should budget for fuel, insurance, maintenance, and unexpected repairs.
- Building simple inspection habits early can catch small problems before they become expensive ones.
The paperwork side of ownership
Buying the car is just the beginning. Within days of driving it home, you have a short list of legal tasks to complete, and the deadlines are real.
Most states require you to register a newly purchased vehicle within 10 to 30 days. Registration ties your name to the vehicle in your state's records and results in the license plates you'll display. The process typically involves your title (the legal document proving ownership), a bill of sale, proof of insurance, and payment of registration fees. Fees vary widely by state and are sometimes based on the vehicle's value or weight.
The title itself is separate from registration. If you paid cash, the title should transfer to you at closing. If you financed the car, the lender holds the title until the loan is paid off. Either way, make sure you understand who has the title and where it is stored.
Some states also require a vehicle safety inspection or emissions test before registration is complete. Check your state's DMV website immediately after purchase so you know exactly what's required and when.
Vehicle title
The legal document that proves who owns a vehicle. When you buy a car with a loan, the lender typically holds the title until the loan is fully paid.
Vehicle registration
The process of officially recording your vehicle with your state government. Registration is renewed annually and results in the license plates displayed on the car.
Liability coverage
The portion of auto insurance that pays for damage or injuries you cause to other people or their property. It does not cover damage to your own vehicle.
Deductible
The amount you pay out of pocket before your insurance policy pays the remainder of a covered claim. A higher deductible usually means a lower monthly premium.
Synthetic oil
A type of motor oil engineered for longer intervals between changes and better performance in extreme temperatures. Many modern vehicles are designed to use it.
Emissions test
A check required in some states to confirm a vehicle is not releasing more pollution than allowed. Passing is often required before registration can be completed.
What insurance actually covers
Auto insurance is mandatory in almost every state, but the minimum coverage required by law is often the bare floor, not a complete safety net.
Liability coverage, which most states require, pays for injuries or property damage you cause to someone else. It does not pay for repairs to your own vehicle. If you financed the car, your lender will require you to carry collision and comprehensive coverage as well. Collision covers damage from accidents; comprehensive covers theft, weather events, and other non-collision incidents.
Deductibles matter, too. That's the amount you pay out of pocket before insurance covers the rest. A higher deductible generally means a lower monthly premium, but it also means a bigger bill if something happens.
Your premium is affected by factors like your driving history, your location, the vehicle's make and model, and how much you drive. As a first-time owner, comparing policy details (not just prices) before choosing a plan is worth the time. This is general information; a licensed insurance agent can help you assess your specific needs.
Routine maintenance in year one
Most new cars arrive in good mechanical shape, but that doesn't mean they run indefinitely without attention. Year one usually involves several scheduled maintenance items.
Oil changes are the most frequent task. Modern vehicles typically need fresh oil every 5,000 to 10,000 miles, depending on whether the car uses conventional or synthetic oil. Your owner's manual has the exact interval for your vehicle. Tire rotations, usually recommended every 5,000 to 7,500 miles, help tires wear evenly and last longer. Many shops combine these two services during the same visit.
By the end of year one, you may also need to replace the cabin air filter (which affects interior air quality) and check the engine air filter. Brake fluid, coolant, and wiper blades are worth a look as well, especially if you bought a used vehicle.
For a more complete picture of what to schedule and when, see our first-time owner maintenance guide. It walks through each task and explains how to build a simple upkeep routine.
Use your owner's manual first
Before searching online for maintenance intervals, check the owner's manual that came with your specific vehicle. Manufacturer recommendations are more accurate than general guidelines and may differ significantly by model and engine type. If the manual is missing, most automakers post digital versions on their official websites.
The real cost of owning a car
A car payment is the most visible expense, but it's far from the only one. First-time owners are often caught off guard by how quickly secondary costs add up.
Fuel is a monthly constant, and the amount depends on your commute, driving style, and the vehicle's efficiency. Insurance premiums can run anywhere from a few hundred to over a thousand dollars per year, depending on your profile and coverage level. Registration fees recur annually. Maintenance, even routine maintenance, adds up over 12 months.
Then there are the less predictable costs: a nail in a tire, a cracked windshield, a battery that dies in winter. These aren't rare events over a full year of driving. Setting aside a small monthly amount, even $30 to $50, into a dedicated car fund gives you a cushion when something unexpected comes up. It won't cover every scenario, but it reduces the sting.
If you financed the car, review your loan terms now so you understand your interest rate, total payoff amount, and whether there are prepayment penalties.
Habits that protect your car and your wallet
Small habits formed in year one tend to stick, and the right ones make ownership significantly less stressful.
Get in the habit of walking around your car before you drive. You'll notice a flat tire, a broken light, or fresh damage before it becomes a safety problem or a surprise at inspection time. Check tire pressure monthly; under-inflated tires wear faster and reduce fuel efficiency. A gauge costs a few dollars and lives in the glove box.
Keep your owner's manual in the car and actually read the maintenance schedule section. Manufacturers design those schedules based on real engineering data, and following them is the most straightforward way to protect your warranty and avoid premature wear.
Park thoughtfully. Door dings and minor collisions in parking lots are among the most common causes of cosmetic damage. Choosing a spot away from heavy traffic, when practical, is a simple way to reduce risk.
Finally, find a repair shop you trust before you need one urgently. Ask people you know for recommendations, read reviews, and visit the shop for a minor service first. Having a reliable mechanic on call makes every future repair easier to navigate.
Frequently Asked Questions
Author
Cars Editorial Team
Cars Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →