
Buying a Used Car vs. a New Car: Weighing the Real Trade-offs
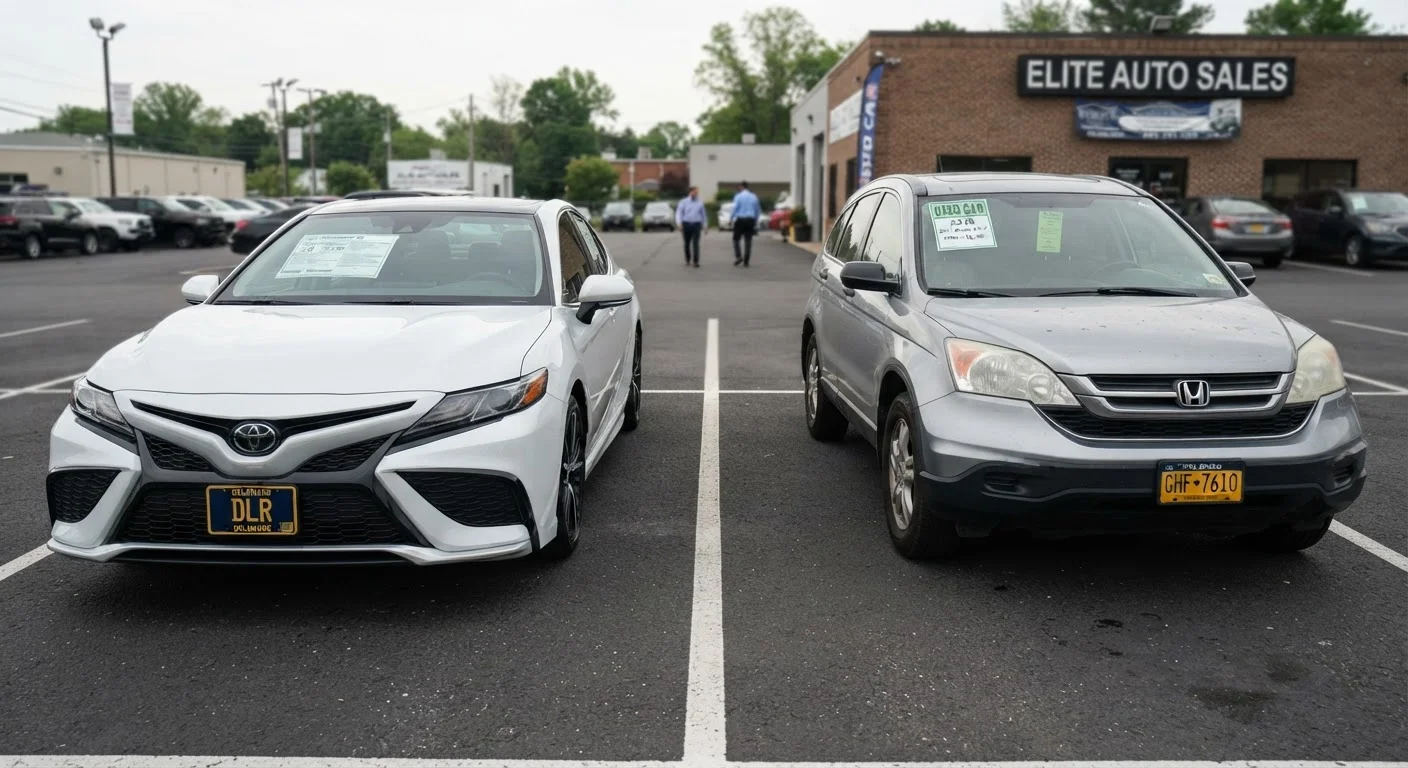
Photo credit: TrendingFaqs.com
In this article
New and used cars each come with distinct financial and practical implications. Here is what to weigh before deciding.
Key Takeaways
- Used cars typically cost less upfront and depreciate more slowly than new ones.
- New cars come with full manufacturer warranties and the latest safety technology.
- Financing rates for new cars are often lower, but the higher purchase price can offset that advantage.
- A used car's history, condition, and remaining warranty coverage vary widely and require careful vetting.
- The right choice depends on your budget, how long you plan to keep the vehicle, and your tolerance for uncertainty.
The cost picture is more complicated than the sticker price
The purchase price is only part of what you pay for a car. Depreciation (the loss of value over time) is the largest cost most car owners never see as a line item. A new car loses a significant portion of its value in the first year of ownership. A used car, having already absorbed that initial drop, depreciates more gradually.
That said, a lower sticker price on a used car does not always mean lower total cost. Older vehicles can carry higher repair expenses, and many lack the fuel-efficiency improvements built into newer models. If a used car needs major work shortly after purchase, the savings can disappear quickly.
Insurance costs add another layer. New cars generally cost more to insure because their replacement value is higher, though safety features can sometimes offset that. Registration fees in many states are also tied to a vehicle's value and model year, so a newer car typically means higher annual fees.
| New car | Used car | Certified pre-owned | |
|---|---|---|---|
| Purchase price | Highest | Lowest | Middle range |
| Depreciation risk | Highest in year one | Lower, already absorbed | Moderate |
| Warranty coverage | Full factory warranty | Varies or none | Extended CPO warranty |
| Vehicle history certainty | Complete, from new | Varies, requires vetting | Inspected, documented |
| Financing interest rates | Often lowest | Often higher | Often competitive |
| Safety technology | Latest standards | Depends on model year | Depends on model year |
| Insurance cost | Generally higher | Generally lower | Moderate |
Financing: lower rates vs. lower balances
Manufacturers and their financing arms frequently offer promotional interest rates on new vehicles. These promotions can make new-car financing genuinely competitive. However, borrowing more money at a lower rate can still mean paying more in total interest than borrowing less at a higher rate. Running the full-term numbers matters more than comparing rates alone.
Used-car loans tend to carry higher interest rates, and lenders sometimes restrict financing on older or high-mileage vehicles entirely. If you are financing, the age and mileage of the used car you are considering can limit your options or raise your monthly payment more than expected.
Reliability, warranties, and the unknown history problem
A new car comes with a manufacturer warranty covering defects and many repairs for a set period, typically three years or 36,000 miles for basic coverage and five years or 60,000 miles for the powertrain. Everything is documented from day one.
A used car's warranty situation varies widely. Some still carry remaining factory coverage. Certified pre-owned (CPO) programs, offered by many manufacturers, extend that coverage and require the vehicle to pass an inspection checklist before sale. A non-CPO used car from a private seller or independent lot may have no warranty at all.
Vehicle history reports (such as those from Carfax or AutoCheck) can surface past accidents, title issues, and service records, but they are not complete. A car can have had unreported damage or deferred maintenance that no database captures. A pre-purchase inspection by an independent mechanic is one of the most useful steps a used-car buyer can take.
Safety technology and features
Federal safety standards evolve, and vehicles built in recent years include technologies that were optional or unavailable in older models. Automatic emergency braking, lane-keeping assistance, and blind-spot monitoring are now standard or common on many new vehicles but may be absent on used cars from five or more years ago.
If specific safety features matter to you, check the model year when they became standard on any vehicle you are considering, not just whether the feature exists somewhere in the product line. A used car from the right model year can have the same safety suite as a new one at a lower price, but that requires research.
Practical questions to answer before you decide
A few concrete questions can focus the decision:
- How long do you plan to keep the car? A longer ownership period makes new-car depreciation less of a concern.
- Do you have a reliable mechanic, or access to one, for independent inspections and future repairs?
- Is your budget fixed, or can it flex to absorb an unexpected repair bill?
- Are there specific safety or technology features you need that may only exist on newer model years?
- Will you finance? If so, compare the full cost of the loan, not just the monthly payment or interest rate.
Answering these honestly narrows the field faster than any general rule about which type of car is the smarter buy.
Author
Cars Editorial Team
Cars Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →