
Net Worth vs. Income: Two Numbers That Tell Very Different Stories
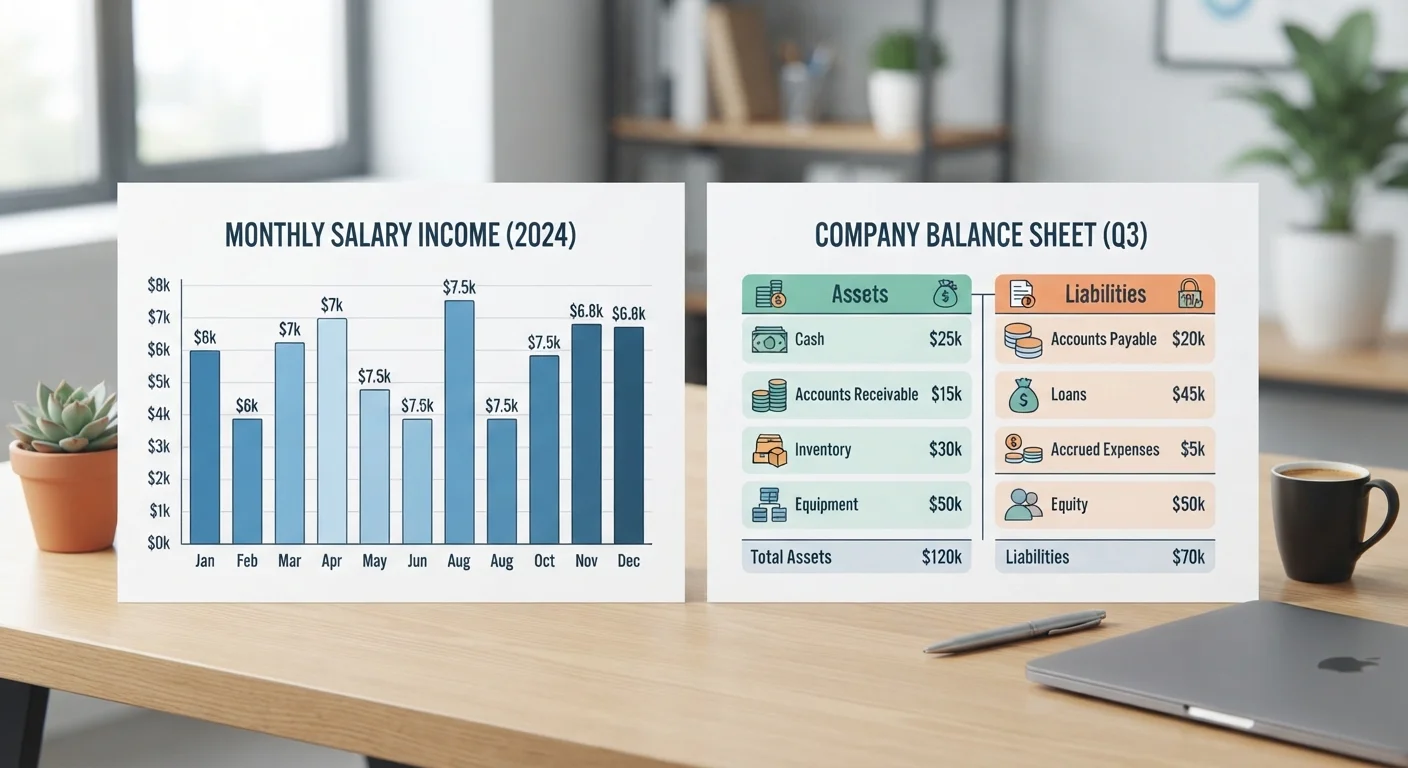
Photo credit: TrendingFaqs.com
In this article
Income and net worth are often confused. Understand what each measures, why the difference matters, and how both shape your financial picture.
Key Takeaways
- Income measures money received over a period; net worth measures accumulated wealth at a point in time.
- High income does not guarantee high net worth if spending and debt outpace saving and investing.
- Net worth is calculated by subtracting total liabilities from total assets.
- Both numbers matter, but net worth is the stronger indicator of long-term financial health.
- Growing net worth depends on what you do with income, not just how much you earn.
What each number actually measures
Income is a flow measurement. It counts money received over a defined period, typically a year or a month. Wages, salaries, freelance earnings, rental payments, and investment dividends all count as income. It answers one question: how much money came in during this period?
Net worth is a snapshot measurement. It adds up everything you own with financial value (assets) and subtracts everything you owe (liabilities). A home, a retirement account, a savings balance, and a car are assets. A mortgage, student loan, credit card balance, and car loan are liabilities. What remains after that subtraction is your net worth. It answers a different question: what is your financial position right now?
The gap between the two concepts matters because they are often conflated in everyday conversation. Someone described as "high-income" is not automatically wealthy, and someone with substantial wealth may draw relatively little income in a given year. Understanding what your paycheck actually represents is one useful starting point, but it only describes income, not the broader picture.
Why high income does not equal high net worth
A physician earning $300,000 a year and a teacher earning $55,000 a year do not automatically end up with proportional net worths. If the physician carries $250,000 in student loan debt, a large mortgage, and spends aggressively, their net worth could be lower than that of the teacher who has no debt, owns a modest home, and contributes consistently to a retirement account.
Net worth grows through the margin between what you earn and what you spend or owe. Income is the raw material, but the ratio of saving, investing, and debt management determines the outcome. How compound interest affects both savings growth and debt accumulation is one reason why the gap between these two numbers can widen dramatically over time in either direction.
| Criterion | Income | Net Worth |
|---|---|---|
| What it measures | Money received over a period | Assets minus liabilities at one point in time |
| Type of measurement | Flow (over time) | Snapshot (at a moment) |
| Common components | Wages, dividends, rental income | Home equity, retirement accounts, debt balances |
| Can be negative? | Rarely | Yes, if liabilities exceed assets |
| Primary use | Budgeting, loan qualification | Retirement planning, overall wealth tracking |
| Changes how often | Each pay period or billing cycle | Continuously, but typically reviewed annually |
How to calculate your own net worth
Add up the fair market value of your assets: bank account balances, retirement account balances, investment account balances, the estimated value of any real estate you own, and the resale value of vehicles or other significant property. Then add up your liabilities: every outstanding loan balance, credit card debt, and any other money you owe.
Subtract total liabilities from total assets. The result is your net worth. For many people early in their careers, that number is negative, particularly if student loans outweigh savings. A negative net worth is not unusual at age 25; it becomes more meaningful as a concern if it persists or worsens into later decades.
Tracking this figure periodically, even once a year, gives you a concrete way to measure whether your financial decisions are adding to or subtracting from your overall position. The time value of money helps explain why earlier contributions to your asset base produce a larger eventual net worth than identical contributions made later.
Using both numbers together
Income and net worth work together rather than in isolation. Income without a growing net worth suggests money is leaving as fast as it arrives. Net worth without adequate income can mean a person is drawing down assets to cover living expenses, which reduces long-term financial stability unless managed deliberately (as in retirement).
Lenders, financial advisers, and government benefit programs each focus on different metrics depending on their purpose. A mortgage underwriter looks at income and debt-to-income ratio. A financial planner assessing retirement readiness focuses on net worth relative to projected expenses. Understanding which number is relevant in a given context prevents confusion and helps you ask better questions.
For a related concept that affects both sides of this equation, the difference between APR and APY matters when debt reduces your net worth or when interest on savings adds to it.
This article is for general informational and educational purposes only and does not constitute personalised financial or investment advice. Consult a qualified financial adviser for guidance specific to your circumstances.

Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →