
Gross Pay vs. Take-Home Pay: Where the Gap Comes From
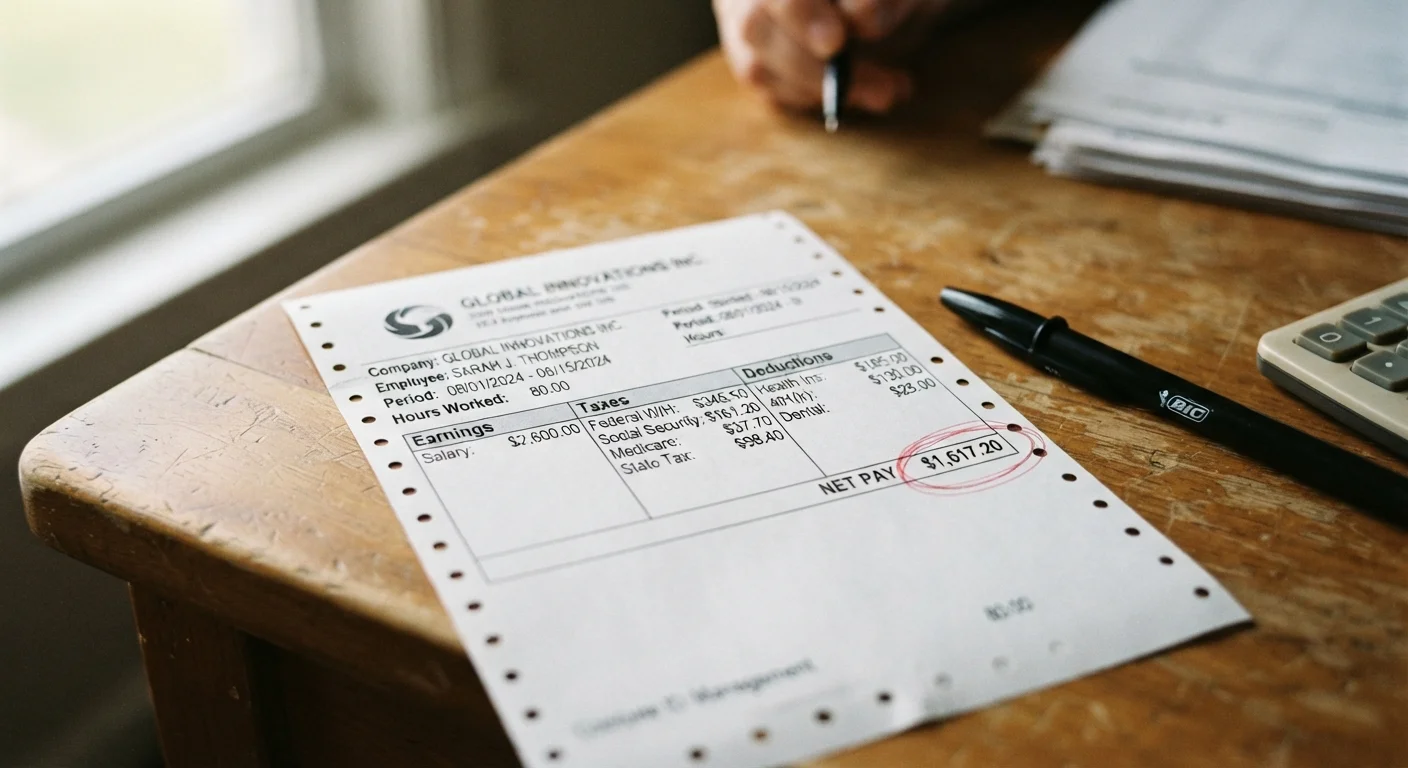
Photo credit: TrendingFaqs.com
In this article
Your paycheck is smaller than your salary for specific reasons. Learn what deductions, taxes, and withholdings create the difference between gross and net pay.
Key Takeaways
- Gross pay is your full salary or wages before taxes and other deductions are applied.
- Take-home pay is what remains after federal, state, and local taxes plus benefit contributions are subtracted.
- Payroll taxes like Social Security and Medicare are mandatory and cannot be opted out of by most workers.
- Voluntary deductions such as 401(k) contributions and health premiums reduce take-home pay but may increase overall financial security.
- Understanding both numbers helps you budget accurately and evaluate job offers more completely.
What gross pay actually means
Gross pay is the total amount your employer agrees to pay you for your work before anything is taken out. For salaried workers, it is your annual salary divided by the number of pay periods in a year. For hourly workers, it is your hourly rate multiplied by hours worked, plus any overtime.
Gross pay also includes bonuses, commissions, and other earnings. When a company says the position pays $65,000 a year, that figure is your gross. It looks larger than what you receive because deductions have not yet been applied. Evaluating what a job offer is really worth means converting that gross number into an estimate of what you will actually take home.
What take-home pay actually means
Take-home pay, also called net pay, is what is deposited into your bank account or printed on your physical check. It is your gross pay minus every deduction your employer is required or authorized to subtract. The gap between gross and net can range from modest to substantial depending on your tax situation, state of residence, and the benefits you have enrolled in.
Because bills are paid with net pay, this is the number that drives real financial decisions. Income and net worth measure different things, but both start with understanding what money you actually have available to work with.
The deductions that create the gap
Several categories of deductions reduce gross pay to net pay, and knowing which is which helps you read your pay stub accurately.
Mandatory payroll taxes
These are set by federal law and apply to almost all workers. Federal income tax withholding is based on the amount you claim on your W-4 form. Social Security tax is currently withheld at 6.2% of wages up to an annual wage base, and Medicare tax at 1.45% with no wage cap. Your employer matches these contributions separately; they do not come from your paycheck twice. State and local income taxes apply depending on where you live and work.
To understand how your federal withholding is calculated relative to your total tax obligation, see the explanation of marginal versus effective tax rates.
| Criterion | Gross Pay | Take-Home Pay |
|---|---|---|
| Definition | Total earnings before deductions | Earnings after all deductions |
| Federal income tax | Not yet subtracted | Already withheld |
| Social Security and Medicare | Not yet subtracted | Already withheld |
| Health insurance premiums | Not yet subtracted | Already deducted |
| 401(k) contributions | Not yet subtracted | Already deducted |
| Used for budgeting | No - overstates spending power | Yes - reflects actual cash available |
| Used for salary negotiation | Yes - the standard reference figure | No - varies by individual deductions |
| Benefit eligibility calculations | Yes - most programs use gross income | Rarely |
Voluntary and employer-sponsored deductions
Beyond mandatory taxes, many workers authorize additional withholdings. Health, dental, and vision insurance premiums are often deducted pre-tax, which lowers your taxable gross before income taxes are calculated. Contributions to a 401(k) or 403(b) retirement account work the same way when made on a pre-tax basis. Flexible spending account (FSA) and health savings account (HSA) contributions are also pre-tax. These deductions reduce take-home pay, but they also reduce your tax bill, so the net effect on purchasing power is smaller than the deduction amount alone suggests.
How to estimate your own net pay
A straightforward way to estimate net pay is to start with your gross pay per period and subtract the items on your most recent pay stub one by one. Group them into mandatory taxes and voluntary benefit deductions. If you are comparing a new job offer to your current pay, you can apply your current effective tax rate as a rough approximation, then adjust for any differences in benefit costs.
If you are negotiating a raise, keep in mind that a higher gross figure does not translate dollar-for-dollar into a higher net. A portion of any raise will go to income taxes, though the overall amount you keep still increases.
7.65%
Mandatory payroll tax rate for most workers
The IRS sets Social Security (6.2%) and Medicare (1.45%) withholding rates for employees, totaling 7.65% of wages up to applicable limits.
10 to 37%
Federal income tax bracket range
The IRS applies a progressive federal income tax schedule with brackets ranging from 10% on the lowest taxable income to 37% on the highest, as of current law.
$23,500
401(k) employee contribution limit (2025)
The IRS sets annual limits on pre-tax 401(k) contributions; for 2025 the limit for employees under 50 is $23,500.
Pre-tax deductions are worth understanding carefully. Contributing to a pre-tax retirement account reduces your taxable income, which lowers your federal and state income tax withholding. That means the contribution costs you less in take-home pay than its face value. A $200 per paycheck contribution might reduce your check by only $145, depending on your tax bracket.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Tax rates and rules vary by individual circumstances and change over time. Consult a licensed tax professional or financial adviser for guidance specific to your situation.

Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →