
The Pros and Cons of Extended Vehicle Warranties
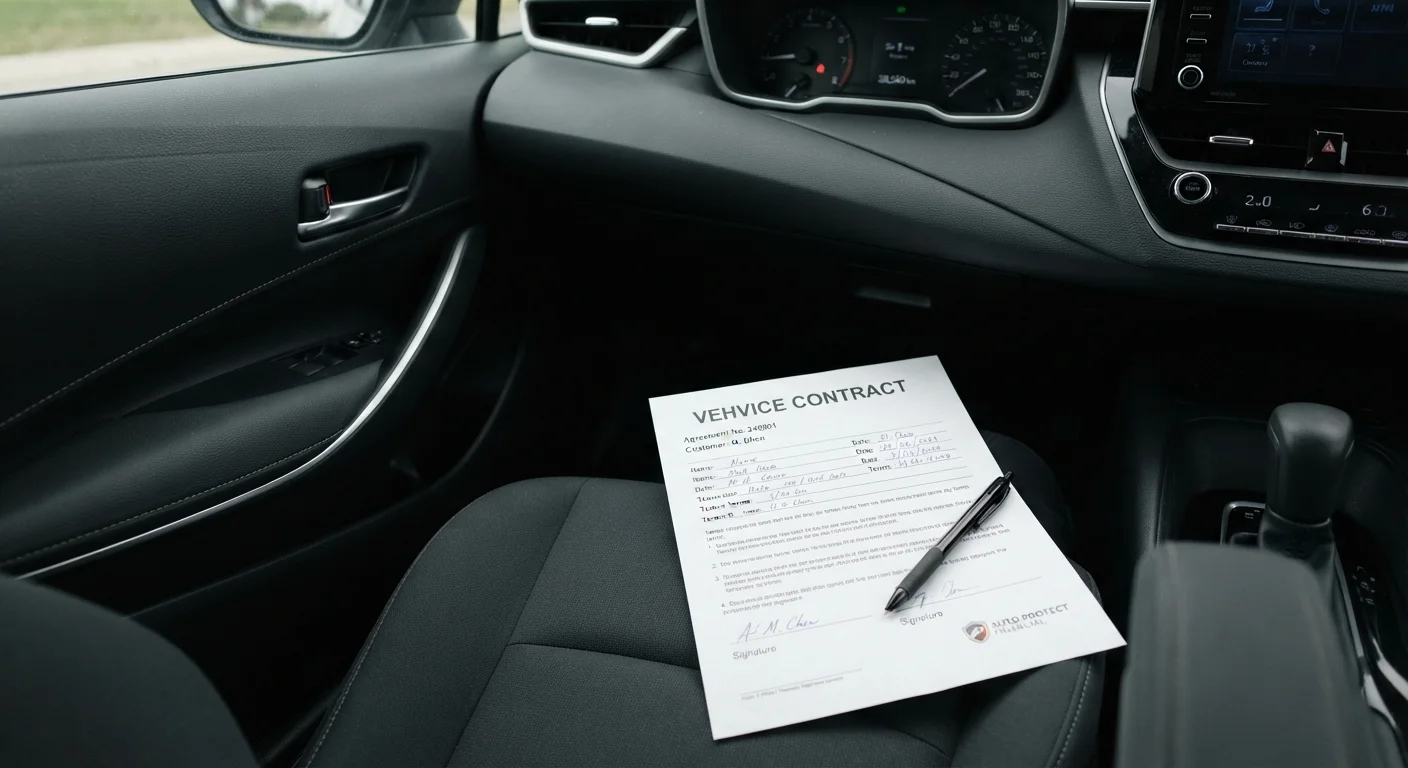
Photo credit: TrendingFaqs.com
In this article
Extended warranties promise peace of mind, but come with costs and limitations. A balanced look at what they offer and where they fall short.
Key Takeaways
- Extended warranties cover certain repairs after the factory warranty expires, but exclusions vary widely by contract.
- The total cost of a warranty can exceed what you would spend paying for repairs out of pocket.
- Third-party warranties carry more risk than those offered directly through a vehicle manufacturer.
- Reading the contract before signing is the only reliable way to know what is actually covered.
Converts unpredictable repair bills into fixed costs
A set monthly or upfront payment replaces the uncertainty of a surprise repair bill, which helps drivers manage a tight monthly budget.
Can cover expensive powertrain and electrical failures
Engine and transmission repairs regularly cost thousands of dollars. A comprehensive plan covering these components can pay for itself in a single claim.
Manufacturer-backed plans reduce claim-denial risk
Programs offered directly through automakers or their certified networks tend to have more reliable claims handling than independent third-party providers.
Useful for high-mileage or older used vehicles
A used vehicle with an unknown service history carries more repair uncertainty. A warranty plan priced accordingly can offset that risk meaningfully.
Many buyers never use the coverage they pay for
Reliable vehicles often complete the warranty term without a covered failure, meaning the full contract cost is paid with no return.
Exclusions can make coverage narrower than it appears
Most contracts exclude wear items, pre-existing conditions, and damage tied to missed maintenance, which can disqualify legitimate claims.
Third-party providers carry financial and reliability risk
Some independent warranty companies have closed or denied large claims on technical grounds, leaving owners with bills they expected to be covered.
Pre-authorization requirements can delay repairs
Many contracts require approval before a shop begins work. Missing that step, even in an emergency, is often grounds to deny the claim entirely.
Total cost can exceed realistic out-of-pocket repair costs
On vehicles with strong reliability records, the combined contract cost plus any deductibles can surpass what the owner would have paid by just covering repairs directly.
What an extended warranty actually is
An extended warranty is a service contract that pays for certain covered repairs once your vehicle's factory (manufacturer) warranty runs out. Despite the name, it is not a warranty in the legal sense: it is a contract with terms set by whoever sells it, whether that is the automaker, a dealership, or a third-party company.
Factory warranties are included in the purchase price of a new vehicle and typically cover the powertrain (engine, transmission, drivetrain) for a set number of years or miles. Extended warranties pick up after that window closes, or in some cases overlap with it. Coverage can range from a basic powertrain plan to a comprehensive "bumper-to-bumper" contract that mirrors the original factory coverage.
Because the terms vary so much between providers, two contracts marketed with similar language can offer very different protection. That gap is where most consumer frustration originates. For a broader look at how coverage limits and exclusions shape what any service contract actually delivers, see what an insurance policy covers and excludes.
The case for buying one
Converts unpredictable repair bills into fixed costs
A set monthly or upfront payment replaces the uncertainty of a surprise repair bill, which helps drivers manage a tight monthly budget.
Can cover expensive powertrain and electrical failures
Engine and transmission repairs regularly cost thousands of dollars. A comprehensive plan covering these components can pay for itself in a single claim.
Manufacturer-backed plans reduce claim-denial risk
Programs offered directly through automakers or their certified networks tend to have more reliable claims handling than independent third-party providers.
Useful for high-mileage or older used vehicles
A used vehicle with an unknown service history carries more repair uncertainty. A warranty plan priced accordingly can offset that risk meaningfully.
The strongest argument for an extended warranty is cost predictability. A single transmission replacement can run several thousand dollars. If a contract costs less than that over its term and the covered failure actually happens, the contract pays for itself. For drivers on a fixed monthly budget, converting an unpredictable repair event into a known monthly or upfront cost has real value.
Extended warranties also tend to matter most on vehicles where out-of-warranty repairs are expensive relative to the car's value. Certain luxury makes and technologically complex vehicles fall into this category. If you are buying used and the vehicle has a track record of costly component failures, a powertrain or comprehensive plan is worth pricing out seriously. The trade-offs between buying used versus new can help put that decision in context.
The case against buying one
Many buyers never use the coverage they pay for
Reliable vehicles often complete the warranty term without a covered failure, meaning the full contract cost is paid with no return.
Exclusions can make coverage narrower than it appears
Most contracts exclude wear items, pre-existing conditions, and damage tied to missed maintenance, which can disqualify legitimate claims.
Third-party providers carry financial and reliability risk
Some independent warranty companies have closed or denied large claims on technical grounds, leaving owners with bills they expected to be covered.
Pre-authorization requirements can delay repairs
Many contracts require approval before a shop begins work. Missing that step, even in an emergency, is often grounds to deny the claim entirely.
Total cost can exceed realistic out-of-pocket repair costs
On vehicles with strong reliability records, the combined contract cost plus any deductibles can surpass what the owner would have paid by just covering repairs directly.
The most consistent criticism of extended warranties is that many buyers never recoup the cost. Vehicles with strong reliability records may go years without a major mechanical failure, meaning the contract expires unused. Even on less reliable vehicles, the repairs that occur are sometimes excluded under the contract's fine print.
Third-party warranty companies carry an additional layer of risk: some have gone out of business or denied large claims through technicalities. Manufacturer-backed extended warranties (sometimes called certified programs) carry less of this risk but are usually more expensive. Before committing to any contract, questions worth asking before signing any insurance policy outlines the kind of scrutiny that applies here too.
Extended warranties also typically exclude wear items (brake pads, tires, wiper blades), pre-existing conditions, and damage from lack of maintenance. If a repair is denied because service records are incomplete, the contract provides no benefit at all. These costs fit into a wider picture of vehicle ownership expenses covered in the hidden costs of car ownership.
Manufacturer vs. third-party contracts
Extended warranties sold through an automaker's official program are backed by the manufacturer and serviced through the same dealer network. Third-party contracts are issued by independent companies and may have their own repair network requirements and claims processes. The two types are not equivalent in terms of claim reliability or coverage breadth, even when marketed using similar language. Always confirm who is actually backing the contract before you sign.
How to evaluate a contract before you sign
The most important step is reading the full contract, not the sales summary. Look specifically for the list of excluded components, because comprehensive-sounding plans often have long exclusion lists. Confirm whether the contract requires you to use a specific repair network or allows any licensed shop.
Ask about the claims process: some contracts require pre-authorization before any repair begins, and failing to get it can void the claim entirely. Check whether a deductible applies per visit or per repair item, since the difference can be significant on a complex job.
Finally, compare the total contract cost against your vehicle's repair history and reliability data from sources like government vehicle safety databases or owner survey publications. If the math suggests you are unlikely to reach the break-even point, self-insuring by setting aside a monthly amount in a dedicated savings account is a practical alternative many owners overlook.
This article provides general information about extended vehicle warranties and is not personalized financial or legal advice. Contract terms, costs, and coverage vary by provider. Read any contract fully and consult a qualified professional if you have questions about your specific situation.
Author
Cars Editorial Team
Cars Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →