
Emergency Funds: What the Concept Means and the Logic Behind the Advice
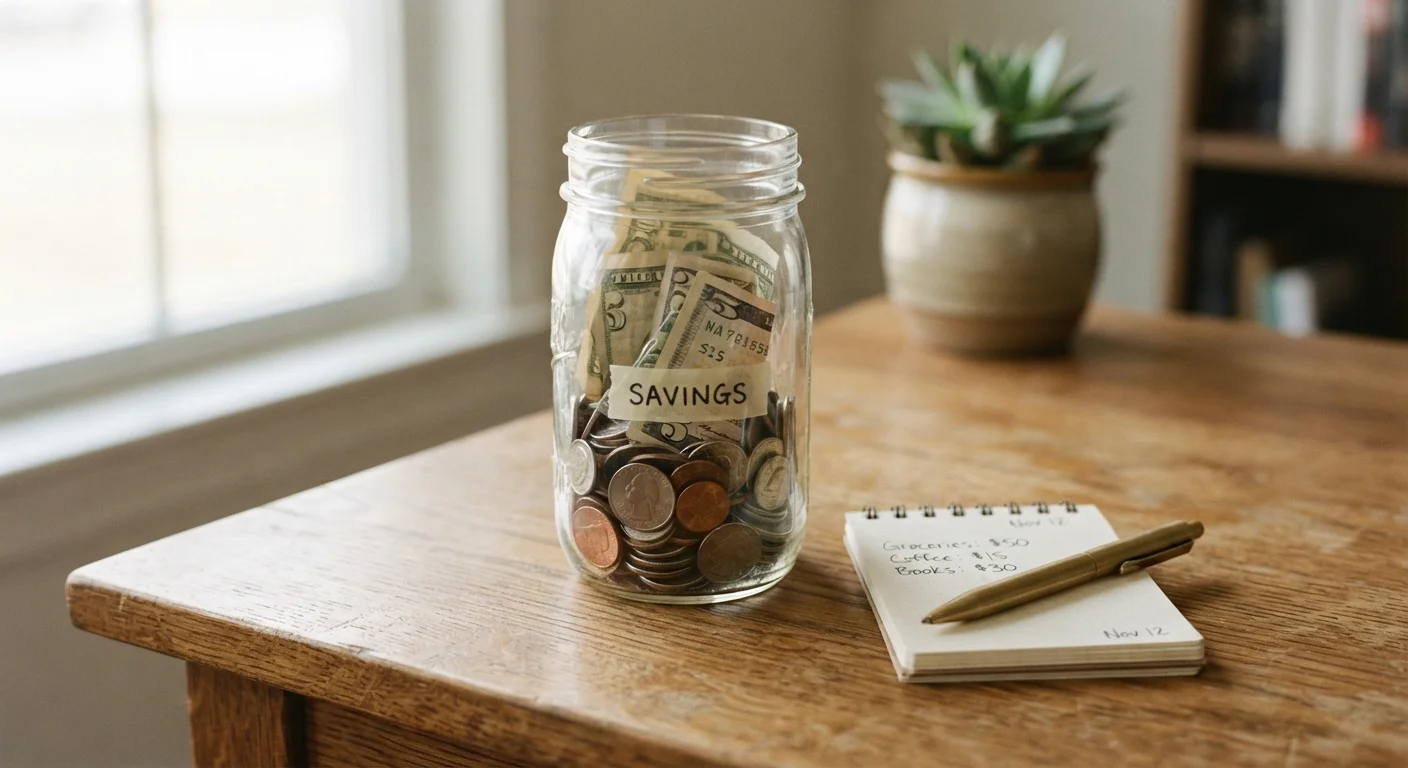
Photo credit: TrendingFaqs.com
In this article
Financial educators consistently recommend emergency funds, but the reasoning is often skipped. Learn what this concept is, why it exists, and how it works.
Key Takeaways
- An emergency fund covers unexpected costs so you do not need to take on debt in a crisis.
- The standard guidance of three to six months of expenses reflects how long it typically takes to find new employment.
- Keeping the fund in a separate, accessible account reduces the temptation to spend it.
- An emergency fund and insurance serve different purposes and are not substitutes for each other.
- Even a small, growing fund provides measurable protection compared to having none at all.
The core idea behind the concept
Financial life regularly produces surprises: a furnace breaks down in January, a medical visit arrives without warning, an employer eliminates a position. Each event demands money that was not in the plan. Without a reserve, the typical response is to borrow, whether through a credit card, a personal loan, or withdrawing from a retirement account early. All three options carry costs that compound the original problem.
An emergency fund exists to interrupt that pattern. It is money already set aside, held outside your normal budget, available to absorb a shock without triggering debt or disruption to long-term financial goals. The concept is not complex, but the reasoning behind it is worth understanding clearly before acting on the advice.
This article is general financial information and is not personalized financial advice. For decisions specific to your situation, consult a qualified financial professional.
Why the advice specifies three to six months
The three-to-six-month figure is grounded in one concrete variable: how long it typically takes an unemployed person to find new work. Job loss is the emergency that demands the most sustained financial coverage. A one-time repair bill can often be covered by a much smaller reserve, but an income gap stretching weeks or months requires a larger cushion.
The range, rather than a fixed number, accounts for variation in personal circumstances. Someone with a stable salary, low fixed expenses, and few dependents may be adequately protected toward the lower end. Someone who is self-employed, supports a family, works in a cyclical industry, or carries high fixed monthly costs generally needs more. Neither end of the range is universally correct.
~4 in 10
Americans who could not cover a $400 emergency from savings
According to the Federal Reserve's Report on the Economic Well-Being of U.S. Households, a substantial share of American adults report they would struggle to cover a mid-sized unexpected expense without borrowing or selling something.
3 to 6 months
Commonly recommended emergency fund target
This range, cited consistently by financial educators including those at nonprofit financial counseling organizations, reflects typical job search timelines and the duration of common financial disruptions.
The advice also reflects a practical truth about borrowing: debt taken on during a crisis often costs more than debt taken on in ordinary circumstances, because options narrow and timelines compress. A fund already in place removes that pressure entirely.
How an emergency fund differs from other financial tools
Understanding what an emergency fund is not helps clarify what it actually does.
It is not insurance. Insurance transfers the financial risk of specific, defined events to a third party in exchange for a premium. An emergency fund holds money you own and can deploy for any reason. Insurance pays after a claim is processed, often weeks later, and only for covered events above the deductible. The fund covers the deductible itself, the waiting period, and everything insurance excludes. The two tools work alongside each other. You can read about how insurance fits into a broader financial plan in the insurance basics hub.
It is not an investment. Money in an emergency fund should not be exposed to market risk. If the fund is invested in stocks or mutual funds and a market downturn coincides with your emergency, the fund may be worth less exactly when you need it most. The trade-off is accepted deliberately: a low-yield savings account earns less than the market over time, but it does not shrink on short notice. The time value of money concept helps explain why holding some cash in a low-yield account is still rational when liquidity matters most.
It is not a general savings account. Pooling emergency money with savings earmarked for a planned purchase erodes the clarity of both. Separate accounts make it possible to know at a glance whether the safety net is intact.
Practical considerations for building and maintaining a fund
The account type matters. A high-yield savings account or money market account at an FDIC-insured institution gives the fund stability, accessibility within one to two business days, and some nominal return. Avoid accounts with lock-up periods or withdrawal penalties.
Automating a recurring transfer, even a small one, is a commonly recommended method for people with limited cash flow. The fund grows without requiring a decision each pay period. For specific approaches when income is stretched, realistic saving strategies on a tight budget covers practical options.
Keep the fund in a separate account
Holding emergency money in a dedicated account, distinct from your checking or general savings, makes it easier to track the balance and reduces the likelihood of spending it on non-emergencies. Some people use an account at a different bank entirely to add a small amount of friction before accessing the funds.
The fund also needs periodic review. If your monthly expenses rise, the target amount should rise with them. After using the fund, rebuilding it promptly returns the protection to its prior level.
Unexpected car costs are among the most common reasons people tap an emergency fund. Understanding which vehicle expenses are genuinely urgent versus deferrable can reduce the draw on the fund over time. Prioritizing car maintenance on a budget addresses exactly that question.
An emergency fund fits within a broader set of money concepts worth understanding before making larger financial decisions. Key money concepts for major financial decisions covers foundational ideas that inform how savings, debt, and investment decisions interact.
Frequently Asked Questions

Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →