
Making Sense of Your Explanation of Benefits (EOB)
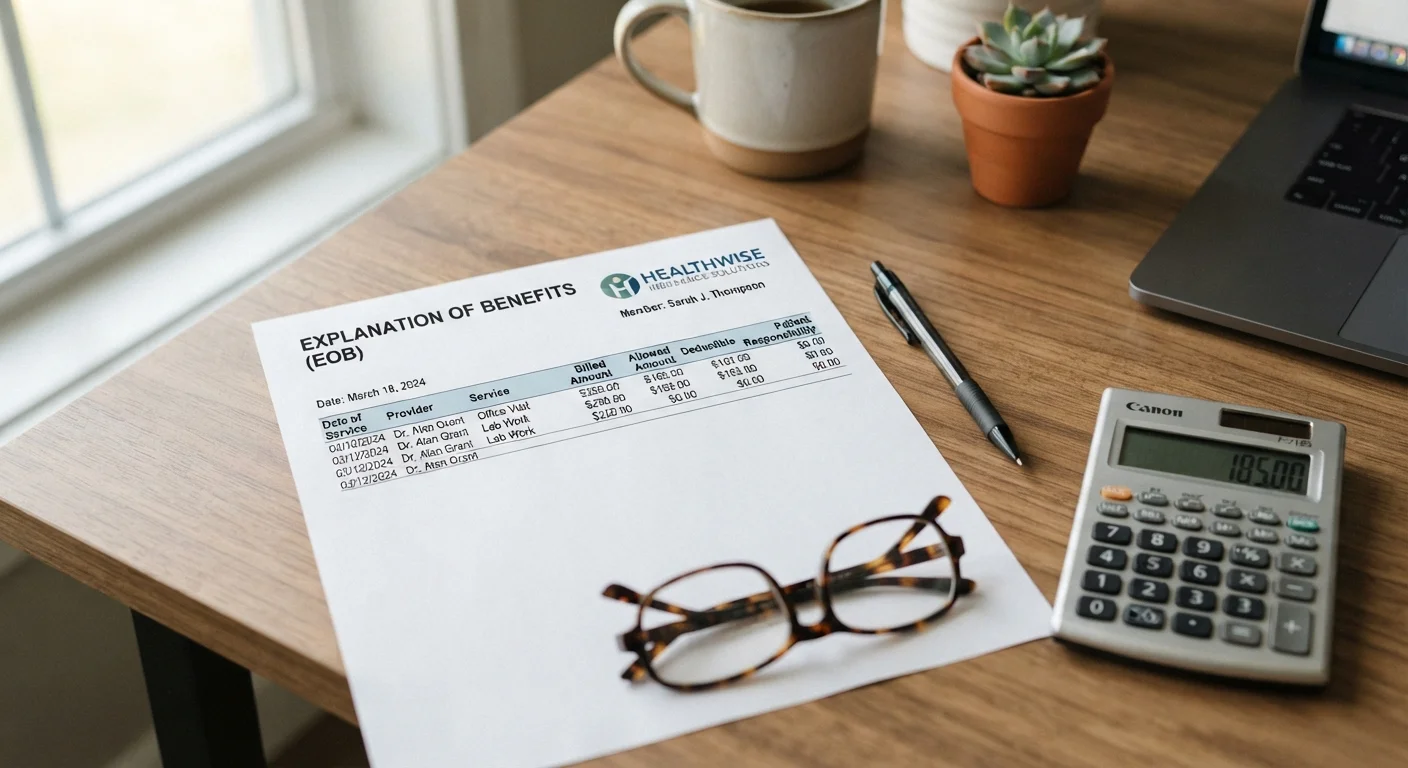
Photo credit: TrendingFaqs.com
In this article
An Explanation of Benefits is not a bill, but it tells you a lot about what your insurer paid and what you owe. Learn how to read each section accurately.
Key Takeaways
- An EOB is a summary from your insurer, not a bill, and requires no immediate payment.
- Each EOB shows the billed amount, the insurer's allowed amount, what the plan paid, and what you owe.
- Comparing your EOB to the provider's bill helps you catch overcharges and billing errors.
- Your deductible, copay, and coinsurance status are all reflected in the EOB's cost breakdown.
- You have the right to appeal a claim denial listed on your EOB.
What an EOB actually is
After you use a health insurance benefit, your insurer mails or posts online a document called an Explanation of Benefits, commonly abbreviated as EOB. The phrase "this is not a bill" is printed on most EOBs precisely because many people mistake it for one. An EOB is your insurer's record of how a claim was processed: it shows what your provider charged, what the plan agreed to pay, and what portion falls to you.
Insurers are required under federal law to send EOBs for most covered services. Your provider will send a separate bill if you owe anything, and the two documents will not always arrive at the same time. Keeping both allows you to verify that they match before you pay anything.
Understanding how your deductible, copay, and coinsurance work together is useful background before reading an EOB, because each of those cost-sharing elements appears as a line item in the document.
What you will need
How to read your EOB step by step
EOB layouts vary by insurer, but every document contains the same core fields. The steps below walk through each field in the order most insurers present them.
Locate the patient and claim information
At the top of every EOB you will find the patient's name, the date of service, the name of the provider or facility, and a unique claim number. Confirm that the patient name and date of service match the appointment in question. If you received multiple services on the same day, each may generate a separate EOB or appear as separate line items on one document.
Read the billed amount column
The billed amount is what your provider charged before any insurance adjustment. This number is almost always higher than what you or your insurer will actually pay, because most providers have contracted rates with insurers. Do not confuse this figure with what you owe.
Identify the allowed amount
The allowed amount (sometimes called the negotiated rate or plan allowed amount) is the maximum the insurer will pay for that service under its contract with in-network providers. If the provider is out-of-network, this figure may be lower and calculated differently, often based on a regional average. The difference between the billed amount and the allowed amount is the provider discount or write-off, which you generally do not owe.
Check what the plan paid
This column shows the dollar amount the insurer sent directly to your provider. It reflects the allowed amount minus any cost-sharing you are responsible for, such as your deductible balance, a copay, or coinsurance. If the plan paid $0, read the remark codes to understand why.
Confirm your patient responsibility
The patient responsibility column is the amount your insurer calculated that you owe. It draws from your current deductible status, any applicable copay, and your coinsurance percentage. Add up the patient responsibility figures across all line items on the EOB to get your total calculated liability for that claim.
Review the remarks or denial codes
Every line item that was adjusted, reduced, or denied will have one or more remark codes. Read the code legend, usually printed at the bottom of the EOB or on a separate page, and note any denial reason that seems incorrect. For example, if a service was denied as a duplicate but you only received it once, that is a billing error worth disputing.
This article provides general information about health insurance documents. It is not legal, financial, or medical advice. Coverage, billing rules, and dispute procedures vary by plan and state. Consult a licensed insurance professional or your plan's member services team for questions specific to your situation.
Common reasons a claim may be denied or reduced
An EOB sometimes shows that the insurer paid less than expected or denied the claim entirely. Common reasons include services coded as out-of-network, a procedure that required prior authorization that was not obtained, or a service the plan classifies as not medically necessary under its specific terms. The EOB will include a remark code, usually a two- or three-character alphanumeric code, next to the affected line. A legend on the back of the document or in a separate insert explains each code in plain language.
If you disagree with a denial or reduction, you can file an appeal. Your EOB must include information about the appeals process, including deadlines. Missing an appeal deadline typically forfeits your right to contest that claim, so note the date on your calendar as soon as you identify an issue.
Your plan type affects which providers generate clean claims in the first place. If you are unsure whether your plan routes you through a network, the comparison of HMO and PPO structures explains how each approach controls provider access and cost-sharing.

Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →