
Travel Insurance: What It Covers and What It Doesn't
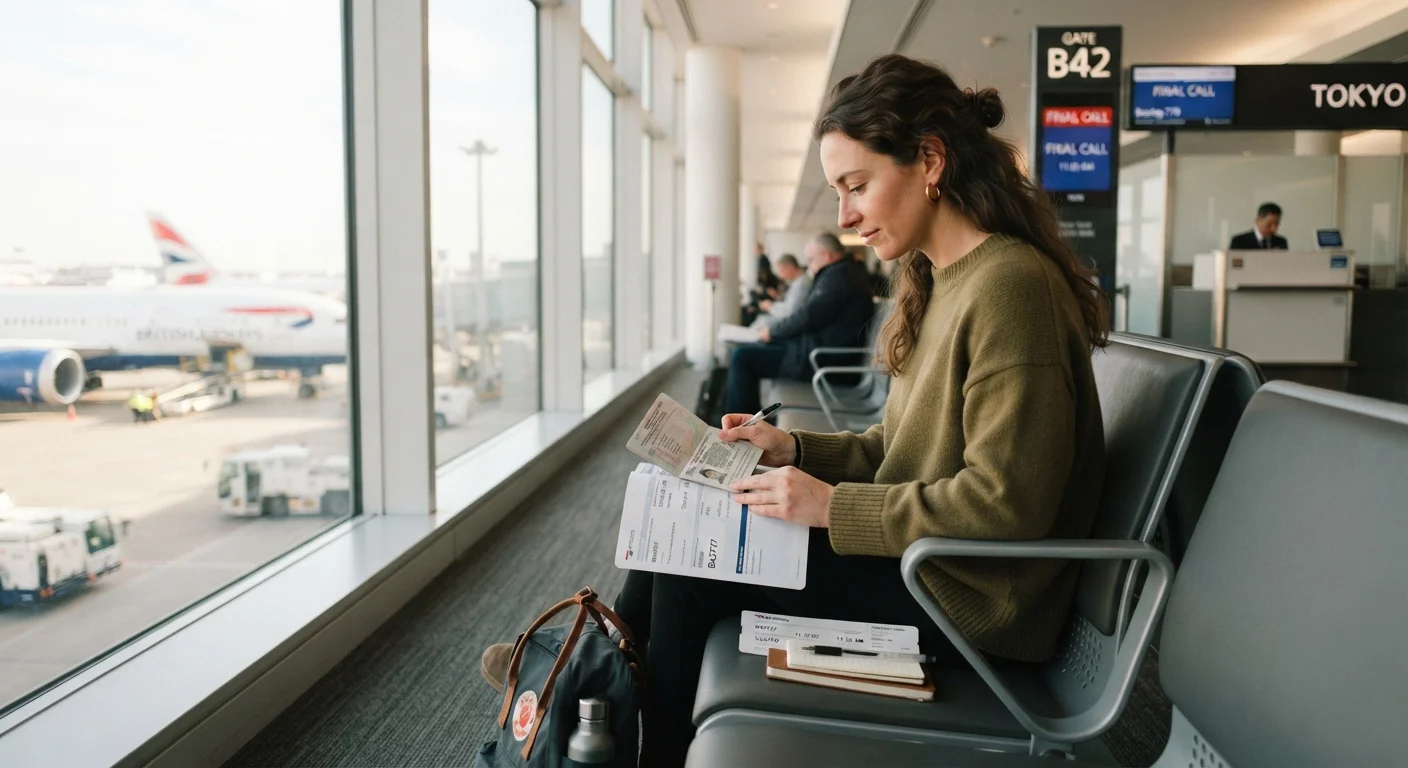
Photo credit: TrendingFaqs.com
In this article
Understand the basics of travel insurance, common coverage types, and the exclusions travelers frequently overlook. Not personalized advice.
Key Takeaways
- Travel insurance generally covers trip cancellation, emergency medical care, and baggage loss, but exact terms vary by policy.
- Pre-existing medical conditions are frequently excluded unless you purchase a waiver within a set window after booking.
- Most policies exclude cancellations caused by fear of travel, foreseeable events, or activities deemed high-risk.
- "Cancel for any reason" coverage costs more and typically reimburses only a percentage of your trip cost.
- Always verify coverage details with the insurer and check official sources for entry and safety requirements before traveling.
What travel insurance is and how it works
Travel insurance is a contract between you and an insurer: you pay a premium, and in exchange the insurer agrees to cover certain financial losses tied to your trip, subject to the policy's terms and exclusions. Most Americans buy travel insurance through their airline booking platform, a travel agent, or directly from an insurance provider.
Policies are usually priced as a percentage of your total insurable trip cost, commonly somewhere between 4% and 10%, though actual pricing depends on factors like your age, destination, trip length, and the coverage level you choose. For context on how insurance policies work generally, see Insurance Basics.
There are two broad structures: comprehensive plans that bundle multiple coverage types together, and standalone plans that cover one specific risk. Comprehensive plans are the most common choice for international travel because they address the widest range of problems in a single purchase.
What travel insurance typically covers
While no two policies are identical, most comprehensive travel insurance plans include some combination of the following coverage types.
Trip cancellation and interruption
This reimburses prepaid, non-refundable costs if you cancel or cut short a trip for a covered reason. Covered reasons usually include sudden illness or injury, the death of a family member, jury duty, or a natural disaster affecting your destination. Cancellations due to work conflicts, change of plans, or general anxiety about travel are generally not covered under standard terms.
Emergency medical and evacuation
This pays for medical treatment if you get sick or injured abroad. It can also cover medical evacuation, which is the cost of transporting you to the nearest adequate medical facility or back home. Medical evacuation costs can reach tens of thousands of dollars, so this coverage matters most for remote or international trips.
Baggage loss and delay
If your checked luggage is lost, stolen, or damaged, a policy with baggage coverage can reimburse you up to a set limit. Baggage delay coverage helps with essential purchases, like clothing or toiletries, if your bags are significantly delayed. Limits and documentation requirements vary by policy.
Travel delay
If your trip is delayed by a covered event such as severe weather or a mechanical issue, travel delay coverage reimburses reasonable additional expenses like meals, accommodation, and transportation. Most policies require a minimum delay, often six to twelve hours, before this benefit activates.
~$4,700
Average cost of emergency medical evacuation abroad
The U.S. Travel Insurance Association has noted that medical evacuations from remote international locations can cost tens of thousands of dollars, with actual amounts varying widely by location and circumstance.
4% to 10%
Typical travel insurance cost as a share of trip price
Insurers and consumer travel resources commonly cite this range, though actual premiums depend on traveler age, destination, and coverage level selected.
14 to 21 days
Common window to add a pre-existing condition waiver
Many insurers require the waiver to be purchased within a set number of days after the first trip deposit; the exact window varies by policy and provider.
What travel insurance often does not cover
The exclusions section of a travel insurance policy is where many travelers get surprised. Knowing these gaps in advance is the best way to set accurate expectations.
Pre-existing medical conditions are among the most common sources of denied claims. If a condition was diagnosed or treated within a lookback period before the policy was purchased, claims related to that condition may be denied unless you purchased a pre-existing condition waiver in time. This is similar to the kinds of coverage gaps that catch policyholders off guard across many insurance types.
Foreseeable events are another standard exclusion. If a hurricane is already named and tracking toward your destination when you buy a policy, that storm will likely not be a covered reason for cancellation. The same logic applies to civil unrest or airline strikes that were publicly known before you purchased coverage.
High-risk and adventure activities, such as skydiving, free climbing, or motorized off-road sports, are frequently excluded from standard policies. Separate riders or specialized policies exist for these activities, but they cost more.
Traveling against official government advisories can void coverage entirely. If a Level 4 Do Not Travel advisory is in place for your destination and you go anyway, your insurer may deny claims that arise from that situation. Always check the U.S. State Department's travel advisories before departing.
Cancellation for any reason that is not listed in the policy as a covered reason is not reimbursable under a standard plan. "Cancel for any reason" (CFAR) upgrades do exist and allow greater flexibility, but they typically reimburse only 50% to 75% of trip costs and must be purchased shortly after the initial trip deposit.
Cruise travelers and specialty coverage
Cruise trips have specific insurance considerations that land-based travel does not. Medical care at sea is limited to the ship's onboard facilities, and the cost of a medical evacuation from a cruise ship can be very high. Standard travel insurance may cover some of these scenarios, but cruise-specific policies or plans that include robust evacuation limits are worth examining for longer voyages.
Cruise cancellation policies also operate differently from airline tickets. Missing a port departure due to a flight delay, for example, can mean losing the entire cruise fare. Some cruise lines sell their own protection plans, but these may have narrower covered reasons than third-party policies. For a broader look at cruise travel planning, see cruise travel guidance.
Before buying any policy, asking direct questions of the insurer prevents misunderstandings later. Questions to ask before signing any insurance policy offers a useful framework that applies across coverage types.
This article is for general informational purposes only and is not personalized insurance or financial advice. Coverage terms, exclusions, and pricing vary by insurer and by state. Read the full policy documents carefully and consult a licensed insurance professional before making coverage decisions.
Frequently Asked Questions
Author
Travel Editorial Team
Travel Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →