
Why Your Credit Score Affects Your Car Insurance Rate
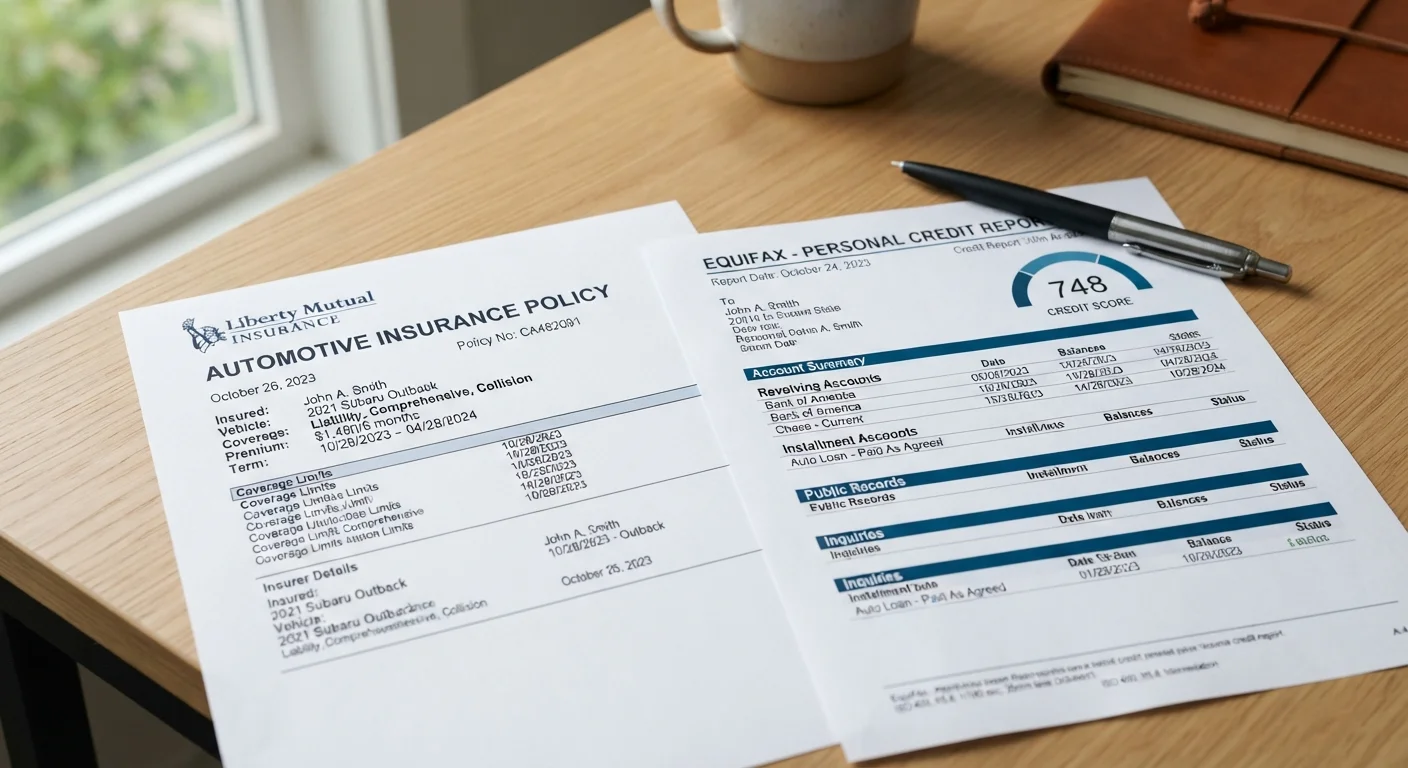
Photo credit: TrendingFaqs.com
In this article
Most US states allow insurers to use credit-based scores in pricing. Learn how and why this practice exists and what it means for you.
Key Takeaways
- Most US states allow auto insurers to use credit-based scores when setting premiums.
- A lower credit-based score can raise your rate even if your driving record is clean.
- Credit-based insurance scores differ from the scores lenders use.
- California, Hawaii, Massachusetts, and Michigan ban the practice for auto insurance.
- Improving your credit over time can lead to lower insurance rates at renewal.
How insurers use credit data
When you apply for auto insurance, most insurers in the US pull a version of your credit history and use it to generate a credit-based insurance score. This number helps them estimate the probability that you will file a claim during the policy period.
The practice is grounded in actuarial data. Insurers have found a statistical correlation between certain credit behaviors and claim frequency. Someone who consistently pays bills on time, keeps balances low, and avoids opening many new accounts tends, on average, to file fewer claims than someone whose credit history shows the opposite pattern. To understand why insurers treat this as relevant, see how risk assessment drives premium pricing.
The score pulls from the same underlying credit file that lenders see, but the formula weights factors differently. Payment history and amounts owed carry the most influence. Length of credit history and the mix of account types also matter, though typically less so.
Credit scoring and underwriting are related but separate
Your credit-based insurance score is one input into a broader underwriting process that also considers your driving record, vehicle type, location, and coverage choices. To see how all those factors interact, it helps to understand how underwriting works before focusing on any single variable.
States where the practice is restricted or banned
Not every driver faces this. California, Hawaii, Massachusetts, and Michigan prohibit auto insurers from using credit information in pricing decisions. A small number of other states have added partial restrictions, such as banning its use during declared disasters or prohibiting it as the sole reason to raise a rate.
If you live outside those states, the odds are high that your credit history is already part of the calculation your insurer uses. You can confirm this by reading your policy declarations page or asking your agent directly. State insurance commissioners publish rules on their websites that explain what is and is not permitted in your state.
What the score actually measures
A credit-based insurance score is not a judgment on your character. It is a statistical tool built on the same data points your lender sees: whether you pay on time, how much of your available credit you carry as a balance, how long your accounts have been open, and how recently you applied for new credit.
Payment history tends to be the heaviest factor. Carrying high balances relative to your credit limits also pulls the score down. To see how that balance-to-limit relationship works, the concept of credit utilization is worth understanding on its own terms.
New credit inquiries and a short credit history can also lower the score, though their effect is usually smaller than payment history or high utilization.
46 states
States that permit credit-based insurance scoring
As of the most recent state-by-state reviews, only California, Hawaii, Massachusetts, and Michigan prohibit the use of credit in auto insurance pricing.
~30%
Weight of payment history in credit scoring models
Payment history is generally the largest single factor in most credit-based models, including those used by insurers, according to widely published credit scoring frameworks.
What you can do about it
The same habits that build a stronger lending credit score generally improve a credit-based insurance score as well. Pay bills by their due dates, keep revolving balances well below the credit limit, and avoid opening several new accounts in a short window.
If your credit has improved since your last renewal, it is reasonable to ask your insurer whether the updated score has been applied. Some insurers require you to request a re-evaluation rather than updating it automatically mid-term.
One thing worth knowing: paying off a debt does not always move your score immediately. Account age, credit mix, and utilization all interact. Paying off debt does not always raise your score right away, so do not expect a single payoff to drop your premium at the next billing cycle.
Your rate can also shift at renewal for reasons that have nothing to do with your own credit or driving record. Premiums can rise even when you file no claims, which is a separate dynamic from credit scoring.
This article is for general informational purposes only and does not constitute financial, insurance, or legal advice. Coverage rules, scoring practices, and state regulations vary. Consult a licensed insurance agent or your state's insurance commissioner for guidance specific to your situation.
Frequently Asked Questions
Author
Cars Editorial Team
Cars Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →